Effective lead generation for financial services must prioritize compliance and suitability from its initial stages. A broad financial promise can inadvertently attract leads that are unsuitable for available products, unserviceable given operational constraints, or noncompliant with regulatory standards. Therefore, an evidence-led approach is paramount, focusing on gathering the necessary information for an appropriate conversation before direct engagement. This strategy ensures that prospecting efforts are targeted, ethical, and aligned with legal and industry requirements, minimizing risks and maximizing the potential for meaningful client relationships. This article explores the operational steps and regulatory considerations for establishing such a framework.
Defining Compliant Lead Generation for Financial Services
Lead generation for financial services fundamentally requires an initial focus on the evidence necessary for an appropriate conversation. This foundational principle is crucial because making broad financial promises can inadvertently attract leads that prove unsuitable for the services offered, unserviceable due to various limitations, or noncompliant with prevailing regulations. Such an approach, rooted in early evidence gathering, establishes a robust framework that minimizes wasted effort and mitigates regulatory risks from the outset. It shifts the paradigm from volume-driven outreach to a more precise, value-driven engagement strategy, ensuring that every interaction is built on a foundation of informed potential. Example: a UK email promoting a retail investment product is blocked when ICO direct-marketing rules for that recipient and channel are unmet, even if a U.S. CAN-SPAM header would have been accurate.
Here is the blocked send I will keep. Product: a UK retail-investment ISA email. Recipient: a former webinar attendee with no current consent record. Channel: email. On 17 August 2026 I rechecked ICO’s direct-marketing guide, the FTC CAN-SPAM compliance guide, and Google’s sender guidelines. The ICO recipient-and-channel rule blocked the send even though a U.S. CAN-SPAM header and subject would have been accurate. Opens are not suitability. If the release rule is missing, the queue stops.
The definition extends beyond merely acquiring contact details; it encompasses the strategic identification and qualification of prospects who genuinely align with specific financial offerings and regulatory parameters. This means understanding not just demographic data, but also the underlying needs, risk profiles, and jurisdictional requirements that dictate the suitability of any financial product or service. Without this initial evidence, lead generation risks becoming a process of random outreach, which can quickly lead to inefficiencies, compliance breaches, and a damaged reputation. A disciplined approach ensures resources are allocated effectively towards prospects with genuine potential.
Ultimately, compliant lead generation for financial services is about proactive risk management and ethical engagement. It mandates that organizations consider the end-to-end client journey, beginning with the very first point of contact. By integrating evidence-based suitability assessments into the earliest phases of lead generation, firms can construct a pipeline of prospects who are not only receptive but also genuinely capable of benefiting from financial advice and products. This structured methodology underpins a sustainable and responsible growth strategy, aligning commercial objectives with regulatory duties and client best interests.
Key Principles of Evidence-Led Outreach
The core of evidence-led outreach involves establishing clear criteria for prospect suitability before any direct marketing commences. This includes defining target buyer types, product relevance, geographical limitations, and any necessary exclusions based on regulatory restrictions or service capacity. For example, a financial advisor specializing in retirement planning for specific income brackets in a particular state would define their leads accordingly. This precision ensures that subsequent outreach aligns directly with the firm's capacity to serve and comply. This initial filtering process is integral to avoiding interactions that are destined to be unproductive or legally problematic, setting a foundation for appropriate engagement.
Operationalizing Compliant Outreach Strategies
Operationalizing compliant lead generation involves a multi-faceted strategy that integrates regulatory guidance with practical workflow. This process begins with a meticulous review of direct marketing guidance, which often varies based on the recipient's location and the communication channel used. For instance, the UK Information Commissioner's Office (ICO) emphasizes that direct marketing rules are contingent on both the recipient and the chosen channel, requiring organizations to diligently consider data protection duties and respect objections to marketing. Similarly, US regulations, such as the CAN-SPAM Act, set specific requirements for commercial emails, impacting how outreach is structured and executed.
- Lead generation for financial services should start with the evidence needed for an appropriate conversation, because a broad financial promise can create leads that are unsuitable, unserviceable, or noncompliant to pursue.
- Direct-marketing guidance on recipient, channel, data protection, and objections.
- Commercial-email guidance on accurate headers, nondeceptive subjects, and opt-out handling.
- By integrating evidence-based suitability assessments into the earliest phases of lead generation, firms can construct a pipeline of prospects who are not only receptive but also genuinely capable of benefiting from financial advice and products.
- The core of evidence-led outreach involves establishing clear criteria for prospect suitability before any direct marketing commences.
For commercial email specifically, compliance mandates accurate header information, non-deceptive subject lines, a clear and conspicuous opt-out mechanism, and a valid postal address for the sender. Google's email sender guidelines further reinforce the need for senders to meet authentication and other delivery requirements, with additional stipulations for bulk senders, ensuring messages reach their intended recipients without being flagged as spam. Adhering to these technical and content-based guidelines is critical for maintaining deliverability and avoiding regulatory penalties, forming a foundational layer of any outbound email strategy for financial services firms.
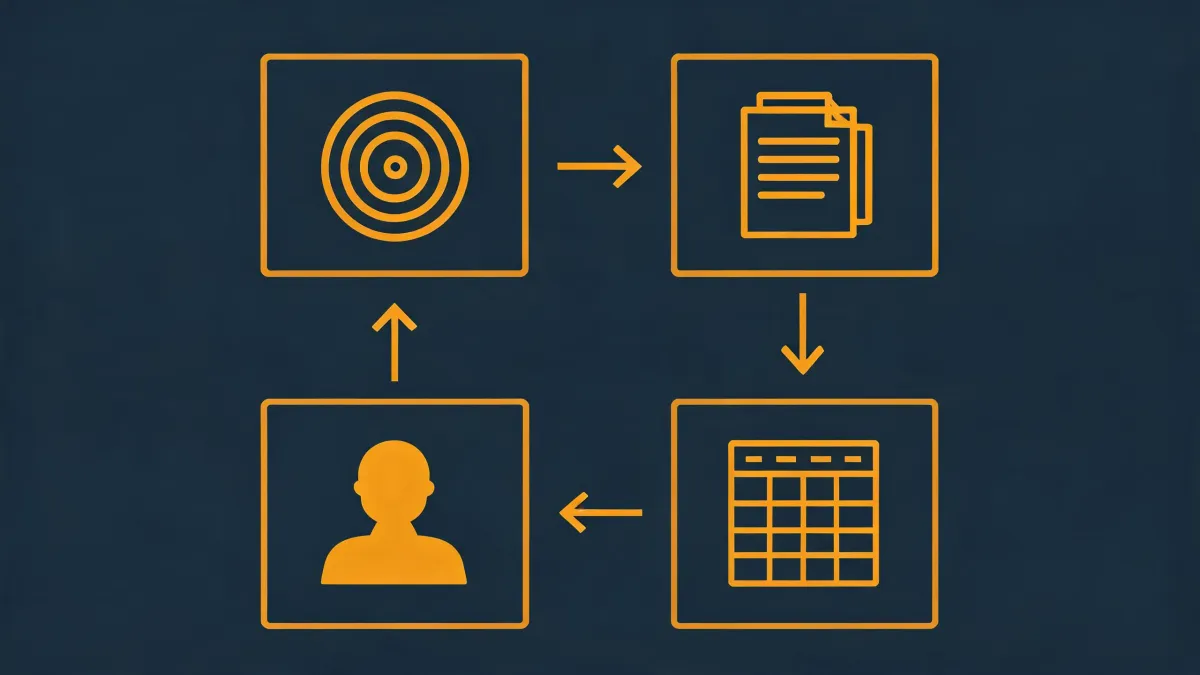
The workflow for compliant outreach should be structured around thorough prospect research and user-confirmed communication. Tools can assist in identifying candidate companies based on natural-language criteria like product focus, buyer type, target country, and specified exclusions. This allows for a curated list of prospects to be reviewed before any contact information is accessed or outreach drafted. Once suitable companies are identified, contact discovery can proceed, followed by the drafting of outreach messages that leverage company context and product materials, ensuring relevance and personalization before a human confirms and sends the communication.
I timestamped those three rules to 17 August 2026 so they cannot be read as timeless folklore. OKKI Go’s send-status FAQ does not change the ICO block.
Structuring the Prospecting Workflow
An effective prospecting workflow integrates several key steps. It starts with prospect research to identify potential leads that align with predefined suitability criteria. For example, a platform like OKKI Go can accept natural-language search criteria, such as specific product types, target buyer personas, or geographical markets, returning candidate companies for review. Users then selectively unlock these companies for further engagement. Subsequently, for unlocked companies, OKKI Go supports contact discovery and can even draft initial outreach messages using company context and product materials. Crucially, the user retains control, confirming the recipient, subject, and body of the message before sending, ensuring human oversight in all communications.
Navigating Jurisdiction-Specific Compliance Boundaries
The application of lead generation rules stops transferring seamlessly across different jurisdictions. What is permissible in one country may be strictly regulated or prohibited in another, necessitating a granular understanding of local laws. For instance, while the U.S. FTC's CAN-SPAM compliance guide sets out clear requirements for commercial email, including accurate headers and opt-out mechanisms, the UK's ICO explains that direct marketing rules are highly dependent on the recipient's location and the specific communication channel. This divergence means a universal 'one-size-fits-all' approach to direct marketing is inherently risky and often non-compliant, underscoring the need for tailored strategies.
Regulatory differences extend to data protection and consent requirements. The ICO's guidance explicitly states that organizations must consider their data protection duties alongside direct marketing rules, particularly regarding how personal data is collected, stored, and used for marketing purposes. This often involves stricter consent requirements than might be found elsewhere, especially for unsolicited communications. Firms operating internationally or targeting prospects in multiple regions must therefore conduct thorough due diligence on each target jurisdiction's specific legal framework concerning privacy, data handling, and marketing permissions, prior to initiating any outreach campaigns.
Furthermore, technical requirements for email deliverability can also vary, influencing where a general rule stops applying. Google's email sender guidelines, for example, outline authentication and other delivery requirements that are essential for messages to reach inboxes, particularly for bulk senders. While these are not strictly jurisdictional laws, they represent de facto standards that impact global email campaigns. Ignoring these technical prerequisites can lead to messages being blocked or routed to spam folders, regardless of the legal compliance of the content. Therefore, a comprehensive strategy must encompass both legal and technical compliance across all target territories.
Understanding Regulatory Divergence
The critical takeaway is that direct marketing and data protection regulations are not universally transferable. An organization must assess the specific rules governing direct marketing based on the intended recipient's location and the chosen communication method. For example, sending commercial emails into the United States requires adherence to the CAN-SPAM Act, which specifies rules for subject lines, opt-out mechanisms, and sender identification. Conversely, marketing to individuals in the UK falls under the purview of the ICO, which places significant emphasis on consent and data protection duties. A failure to adapt strategies to these distinct legal landscapes can result in significant penalties and reputational damage.
Common Misconceptions in Financial Lead Generation
One pervasive misconception in financial lead generation is that any form of interaction, such as an email open or click, automatically signifies buying intent. This is a tempting interpretation to reject because such observations are merely indications of engagement, not definitive proof of a prospect's readiness to purchase or even suitability for a financial product. For instance, a recipient might click on a link out of curiosity or by accident, rather than genuine interest in the financial service being promoted. Relying solely on these metrics for qualification can lead to misdirected sales efforts and a pipeline filled with unsuitable leads, wasting valuable resources and time for financial advisors.
Another common mistake is neglecting the importance of a clear and accessible opt-out mechanism in commercial emails, or failing to honor opt-out requests promptly. The U.S. FTC's CAN-SPAM compliance guide explicitly requires a clear way for recipients to opt out of future emails and mandates that senders process these requests within 10 business days. Similarly, the UK ICO emphasizes respecting objections to marketing. Failing to adhere to these rules not only leads to non-compliance but also erodes trust and can damage a firm's reputation, making future compliant outreach more challenging. This oversight is a critical misstep that can quickly undermine an entire lead generation effort.
Furthermore, many organizations incorrectly assume that a broad, generic financial promise will cast a wider net and generate more leads. This approach often creates leads that are unsuitable or unserviceable, leading to inefficient follow-ups. Instead, lead generation for financial services should start with the evidence needed for an appropriate conversation, ensuring that initial outreach is targeted and relevant. A lack of specificity in initial messaging can also lead to a higher rate of complaints or objections, as prospects may feel misled or find the communication irrelevant to their actual needs. Precision in targeting and messaging is paramount for effective and compliant engagement.
Avoiding Unsuitable Prospecting Practices
The tempting interpretation to reject is the notion that observed interactions, such as email opens or clicks, equate to confirmed buying intent. As reported by OKKI Go, while sending status and failure reasons are exposed, opens or clicks are merely interaction observations and do not constitute proof of buying intent. This distinction is crucial for financial services, where suitability and compliance require a deeper level of qualification. Over-interpreting these initial signals can lead to pursuing prospects who are not genuinely interested or for whom the financial product is unsuitable, resulting in wasted effort and potential regulatory issues. True qualification requires more substantive engagement and evidence.
Implementing an Illustrative Release Decision Framework
To apply sound judgment in lead generation, financial services firms can implement an illustrative release decision framework. This framework acts as a final checkpoint before any outreach campaign is launched, ensuring all aspects of suitability, compliance, and serviceability have been thoroughly addressed. The process begins with a comprehensive review of the target audience, verifying that each segment aligns with the firm's service offerings and regulatory permissions. This includes confirming jurisdictional requirements, data protection protocols, and the ethical implications of the chosen communication channels. Without this systematic review, campaigns risk proceeding with inherent, unaddressed vulnerabilities.
The framework also necessitates a detailed assessment of the outreach content itself. This involves scrutinizing subject lines for non-deceptive language, ensuring message bodies are clear and accurate, and confirming that all required disclosures, such as a valid postal address and an easy opt-out mechanism, are conspicuously present. For instance, any email drafted through a tool like OKKI Go, which can generate outreach from company context and product materials, must still undergo human confirmation of the recipient, subject, and body before sending. This human oversight is critical for mitigating risks associated with automated content generation and ensuring adherence to specific compliance mandates.
Finally, the decision framework should incorporate a clear process for handling objections and managing data. This includes having robust systems in place to process opt-out requests promptly and effectively, as required by regulations like CAN-SPAM or the UK ICO. It also means establishing protocols for monitoring campaign performance, not just in terms of opens and clicks, but more importantly, in terms of lead quality and initial qualification success. This iterative process allows for continuous refinement of strategies, ensuring that future campaigns are even more targeted, compliant, and ultimately, more effective in generating suitable leads for financial services.
Assessing Outreach Readiness
The next decision checkpoint involves a definitive 'go/no-go' for a lead generation campaign based on the cumulative evidence. An illustrative release decision would involve confirming: 1) Each prospect meets predefined suitability criteria, evidenced by initial research (e.g., using criteria refined by tools like OKKI Go). 2) The outreach method and content fully comply with all applicable direct marketing and email regulations in the target jurisdiction (e.g., FTC CAN-SPAM, UK ICO, Google sender guidelines). 3) Clear mechanisms for opt-out and objection handling are in place and tested. 4) The firm has the capacity to service any generated leads appropriately. Only when all these conditions are met should outreach proceed, ensuring a responsible and effective lead generation effort. This ensures that a broad financial promise does not create leads that are unsuitable or noncompliant to pursue.
Separate suitability from lead capture. Financial outreach inherits channel rules and cannot treat interaction as a recommendation trigger.
Frequently asked questions
What must financial-services lead generation separate from capture?
Suitability. A captured inquiry is not a permission to recommend a product. Capture and advice sit under different duties.
Which email rules still apply to financial outreach?
Accurate headers and subjects, identity, and an opt-out path under CAN-SPAM where it applies, plus jurisdiction-specific direct-marketing rules such as ICO guidance in the UK.
Why are opens not suitability evidence?
An open or click is an interaction. It does not establish product fit, permission to advise, or the client’s circumstances.
When should a financial firm block a send?
When the product, jurisdiction, or channel lacks a current release rule, or when the record cannot show a lawful basis for that contact.